

 44 / 98

When I was appointed as CFO in August 2015,
I highlighted three clear priorities that I believe
have been important for this financial year’s
results which will have a significant impact on
our future financial performance. These include
ensuring the returns from accelerated capital
investment, improving the monetisation of
growing data usage and a continued focus on
cost efficiency. While we are on track with all
three of these priorities, there remains scope
for us to do more.
The Group delivered excellent results in a tough operating
environment. Group revenue increased 7.5%, with service revenue
up 7.4%. In South Africa, we have seen a return to growth for service
revenue of 4.9%, with the second half of the year pleasingly
stronger than the first half. Service revenue improved in our
International operations by 16.2% (9.6%*) with the second half also
growing faster than the first half. Group EBITDA grew 12.8% (10.2%*)
ahead of revenue and we delivered strong operating free cash flow
growth of 21.8%.
Investing for network superiority
An important competitive advantage lies in the superiority of our
networks. Over the past two years, we accelerated investment and
spent R26.2 billion on our networks, widening voice and data
coverage and capacity, and continually improving our network
quality as a key differentiator. During our first year, we invested
R13.3 billion, representing 17.9% of Group revenue. This year, in line
with our guidance, we invested R12.9 billion, or 16.1% of Group
revenue. Over the last two years we added 3 471 2G sites, 5 243 3G
sites and 5 198 LTE/4G sites across the Group. To future-proof for
rapidly growing data traffic and to keep incremental cost low, we
have continued to invest in high-speed microwave or fibre
connectivity to 88.5% of our sites in South Africa. To further facilitate
our transition from a predominantly mobile company to a unified
communications provider, we invested over R1.0 billion in our
Customer 3D project. This is one of our largest transformative
projects that will see the modernisation of our billing and customer
interaction system to support our changing customer needs
and demands.
Monetising data
Group data revenue increased 28.5% to R21.3 billion, following
exceptional growth in the demand for data. The improved
affordability both of devices and data bundles supported a 53.7%
increase in data traffic. Although we expect usage growth to be
ahead of revenue growth, we continue to see improvement in data
monetisation, while also moving customers to a more worry-free
experience in their in bundle data usage. Group data revenue
comprises 31.9% of service revenue, up from 26.7% a year ago. In
South Africa, the average monthly data used by customers on smart
devices continues to increase, with the resulting benefits to ARPU
highlighting the value in encouraging customer migration to 3G
and LTE/4G devices. We are seeing an approximately 20% uplift
in ARPU when a customer migrates to these devices. Device
affordability is an important enabler for data growth. While the
declining rand/dollar exchange rate created upwards price pressure,
we have been able to secure competitive prices through our
combined purchasing power with Vodafone. This year, more than
a quarter of all device sales were Vodacom branded devices.
Deliver margin expansion through cost efficiency
Our Group EBITDA margin was 37.9%, delivering a 1.8 ppts margin
expansion, with 1.6 ppts expansion in South Africa to 40.2%, and
3.2 ppts in the International operations to 29.3%. We have made
good progress on cost efficiency with our ‘Fit for growth’
programme, with total expenses growing 5.1%; this is 2.4 ppts below
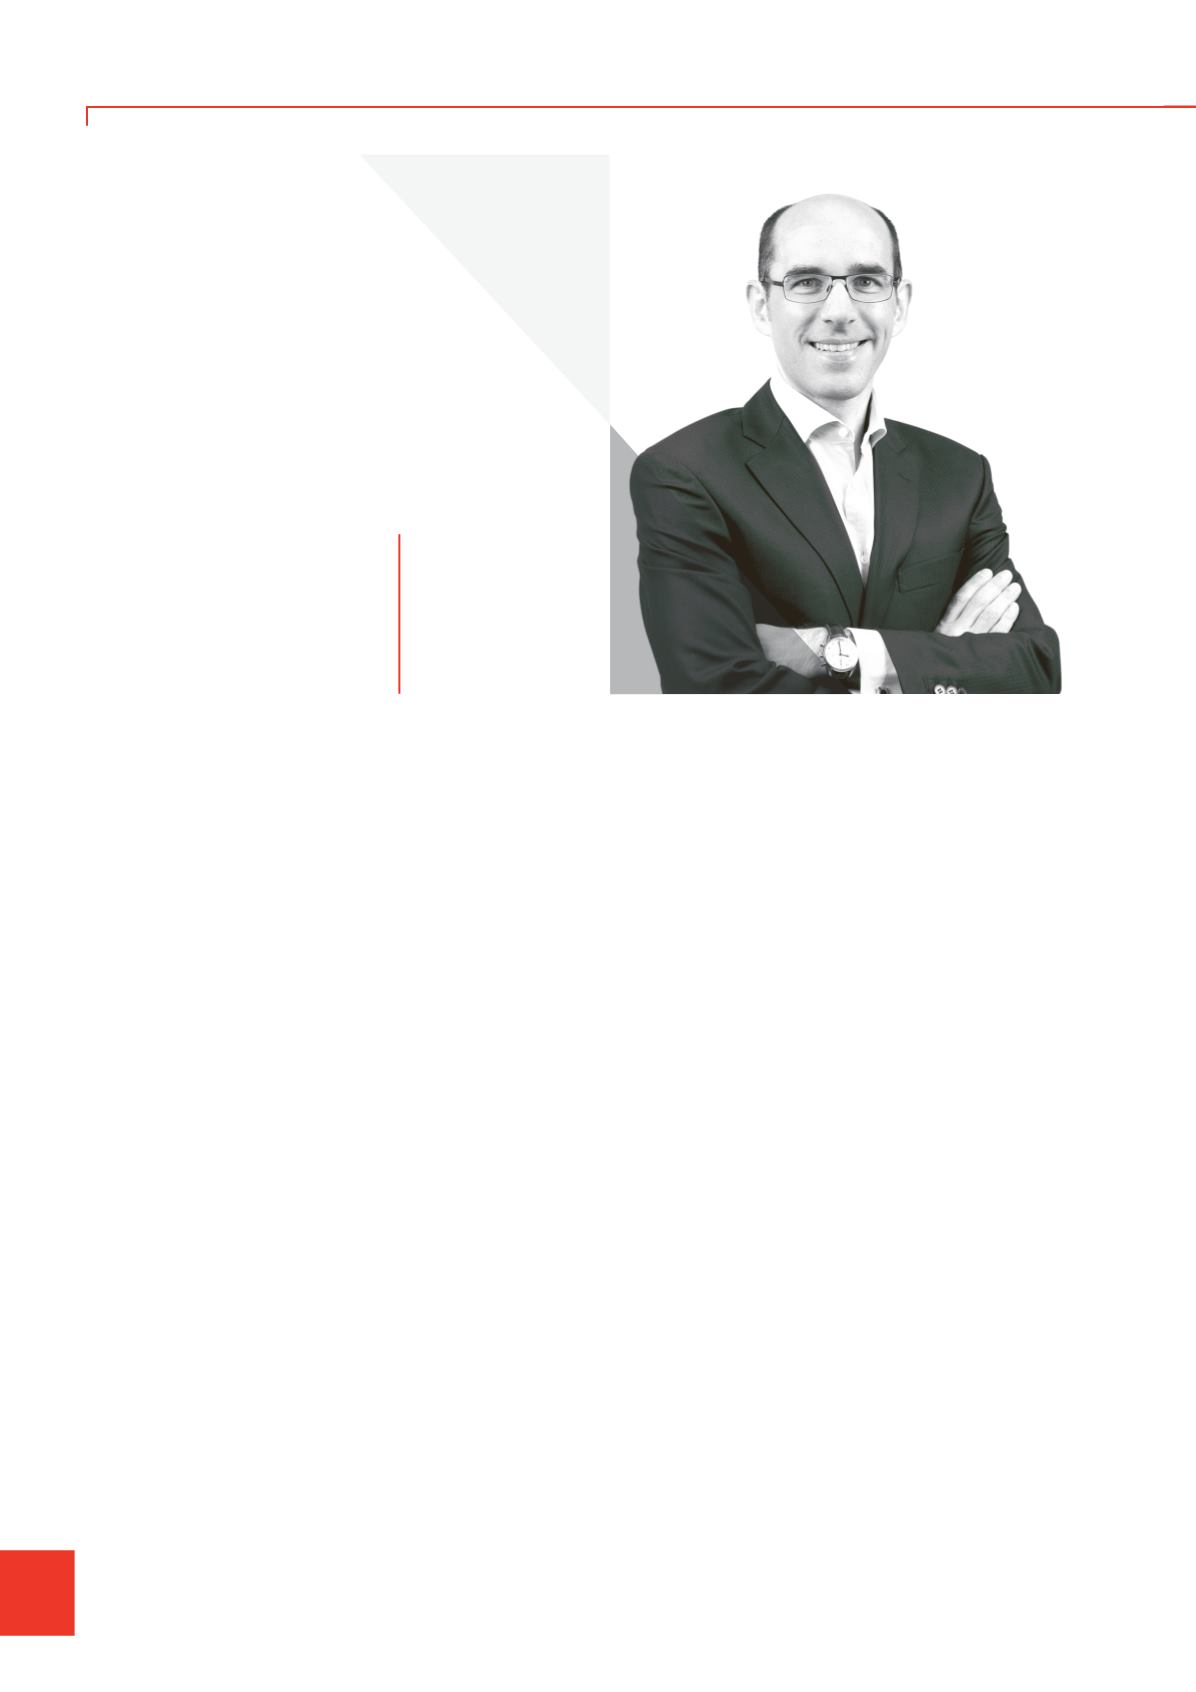
Till Streichert
Vodacom Group Limited
Integrated report for the year ended 31 March 2016
40
CFO’s
review