

 15 / 98

11
+5.1%
Increase in total
expenses
Our performance
Our business
Governance review
Administration
Overview
Key revenue differentiators
À
À
Rated first in network quality in four of five countries
of operation.
À
À
A diverse and widespread distribution network across
all our operations.
À
À
Industry-leading customer value management (CVM)
systems, people and processes.
À
À
Leveraging of global enterprise relationships for pan-African
service delivery.
À
À
Best-in-class customer service support systems.
Key cost differentiators
À
À
Leveraging global best practice on cost optimisation
through our ‘Fit for growth’ programme.
À
À
Benefiting from purchasing power of Vodafone
Procurement Company.
À
À
Consistent investment in network, delivering continuous
improvement in operating costs through more efficient
technologies and network innovation.
À
À
Robust governance processes for approving investments
and reviewing product, cost and investment decisions.
We generate profit by efficiently utilising mobile and fixed-line assets to provide our consumer and enterprise
customers with valued voice, data, messaging and related services. Our competitive differentiation rests in the
quality of our network, in the nature and quality of our products and services, and in how we manage our
cost base.
How we create value
Our revenues
Most of our revenue comes from selling mobile voice, messaging
and data services to individual consumers, with the balance coming
from the sale of these mobile services as well as connectivity and
network provision services to our enterprise customers (page 30).
The recent decline in mobile voice revenue has been more than
offset by growth in data revenue, fuelled by the increased uptake of
smart devices, improved network coverage, more affordable data
bundles and enhanced digital content.
À
À
41.6% of our individual users pay on a monthly basis via
fixed-term contracts (‘postpaid’), while the balance top up
their airtime on a ‘prepaid’ basis.
À
À
68.4% of mobile contract revenue is in-bundle, reducing our
exposure to the risk of discretionary spend in out of bundle
usage.
Our costs
We have a strong track record of optimising expenses and
converting revenue into cash flow. We have achieved significant
results in limiting cost growth through our ‘Fit for growth’
programme, managing staff expenses, publicity spend and other
operating expenses. This has been enabled through an improved
culture of cost containment across the business. Our resulting
strong cash flow helps us to maintain a high level of capital
reinvestment, primarily in our network infrastructure to maintain our
leading position in network coverage, call quality and data speed in
all our markets. We have also focused some capital spend on our
new billing system as we transition from a predominately mobile
company to a unified communications provider. In addition to
investing in the future prosperity of the business, cash generated
from our activities allows us to maintain our generous shareholder
returns, with our dividend policy of at least 90% of HEPS.
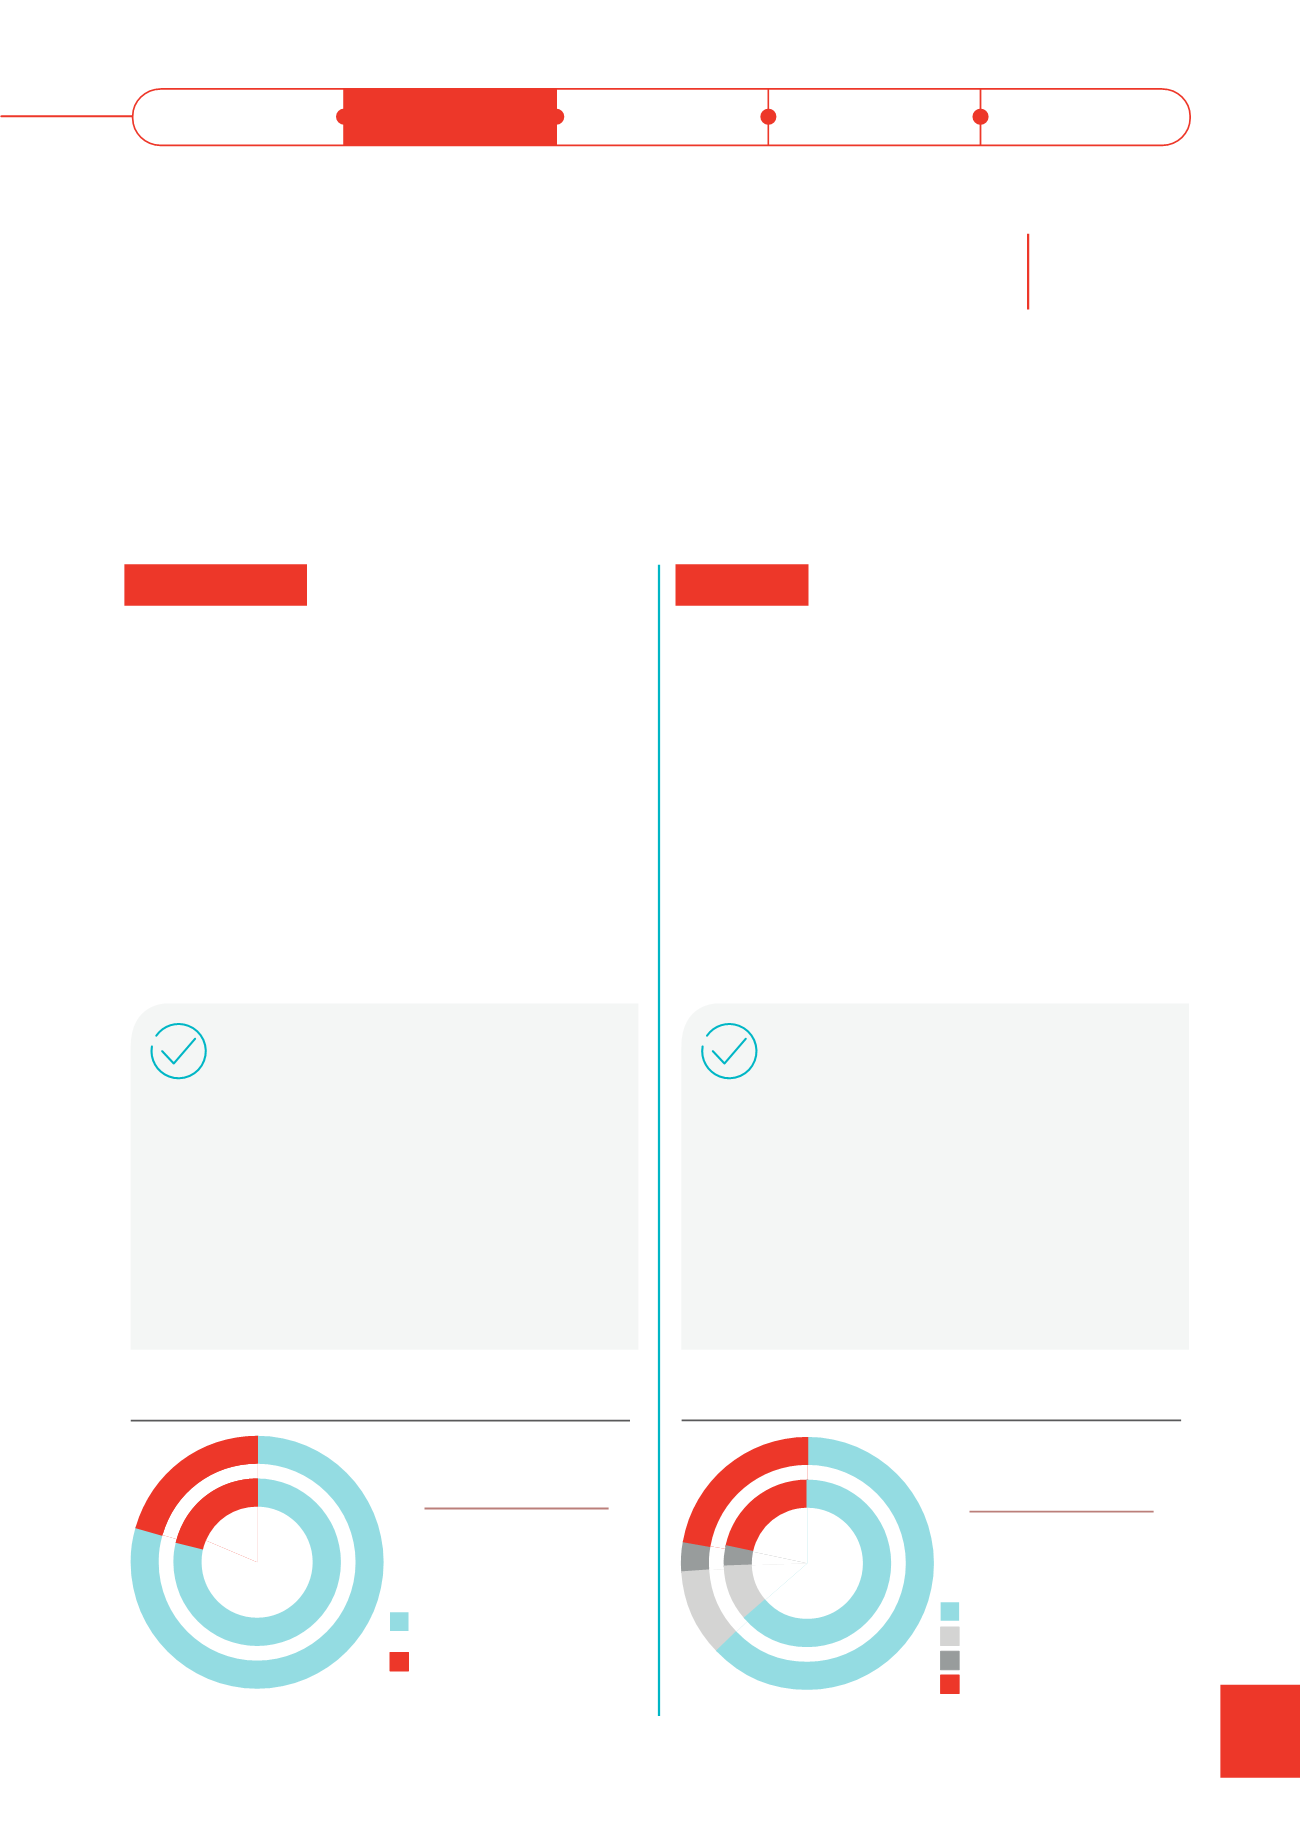
64%
63%
Direct expenses
10%
11%
Staff expenses
4%
4%
Publicity expenses
22%
22%
Other opex
2015
2016
2016
2015
Group total expenses composition (%)
82%
79%
Consumer
service revenue
18%
21%
Enterprise
service revenue
2015
2016
2016
2015
Group service revenue composition (%)
+7.4%
Increase in service
revenue